 Featured partnerSign up to Lightyear and get up to €100 in a free fractional shareCapital at risk, terms apply. Seek guidance if necessary. Claim Up to €100 Capital at risk, terms apply. Seek guidance if necessary.
- Curve sits on top of your existing cards, letting you carry one Mastercard and switch a payment to a different card after the fact with Go Back in Time.
- The free Curve Pay plan now allows unlimited cards. The old cap on payment sources has gone. The free plan still allows 3 Go Back in Time switches a month, and €250 of foreign spending before a 2.99% fee.
- Support and reliability are the weak points, with reported 3 to 4 week response times, no phone line, app crashes and a Trustpilot rating of 2.4 out of 5.
- For most EU users, Wise or Revolut still look like better value on fees and support. Unlimited cards restore aggregation on the free plan, but switching and fee-free foreign spending stay tightly capped.
Curve Card promises to consolidate all your payment cards into one smart Mastercard. After extensive testing, we found the concept compelling but the execution seriously lacking. Here's what EU users need to know before signing up.
Curve at a glance
What We Like About Curve Card
The core concept remains innovative. Curve sits between you and your existing cards, allowing you to:
- Consolidate multiple cards into one physical Mastercard
- Switch transactions retroactively with "Go Back in Time" (up to 120 days)
- Manage spending through one app interface
- Automate card selection with smart rules
The Go Back in Time feature genuinely solves real problems. Moving a personal expense from your business card or switching to a rewards card after purchase works seamlessly when it functions properly.
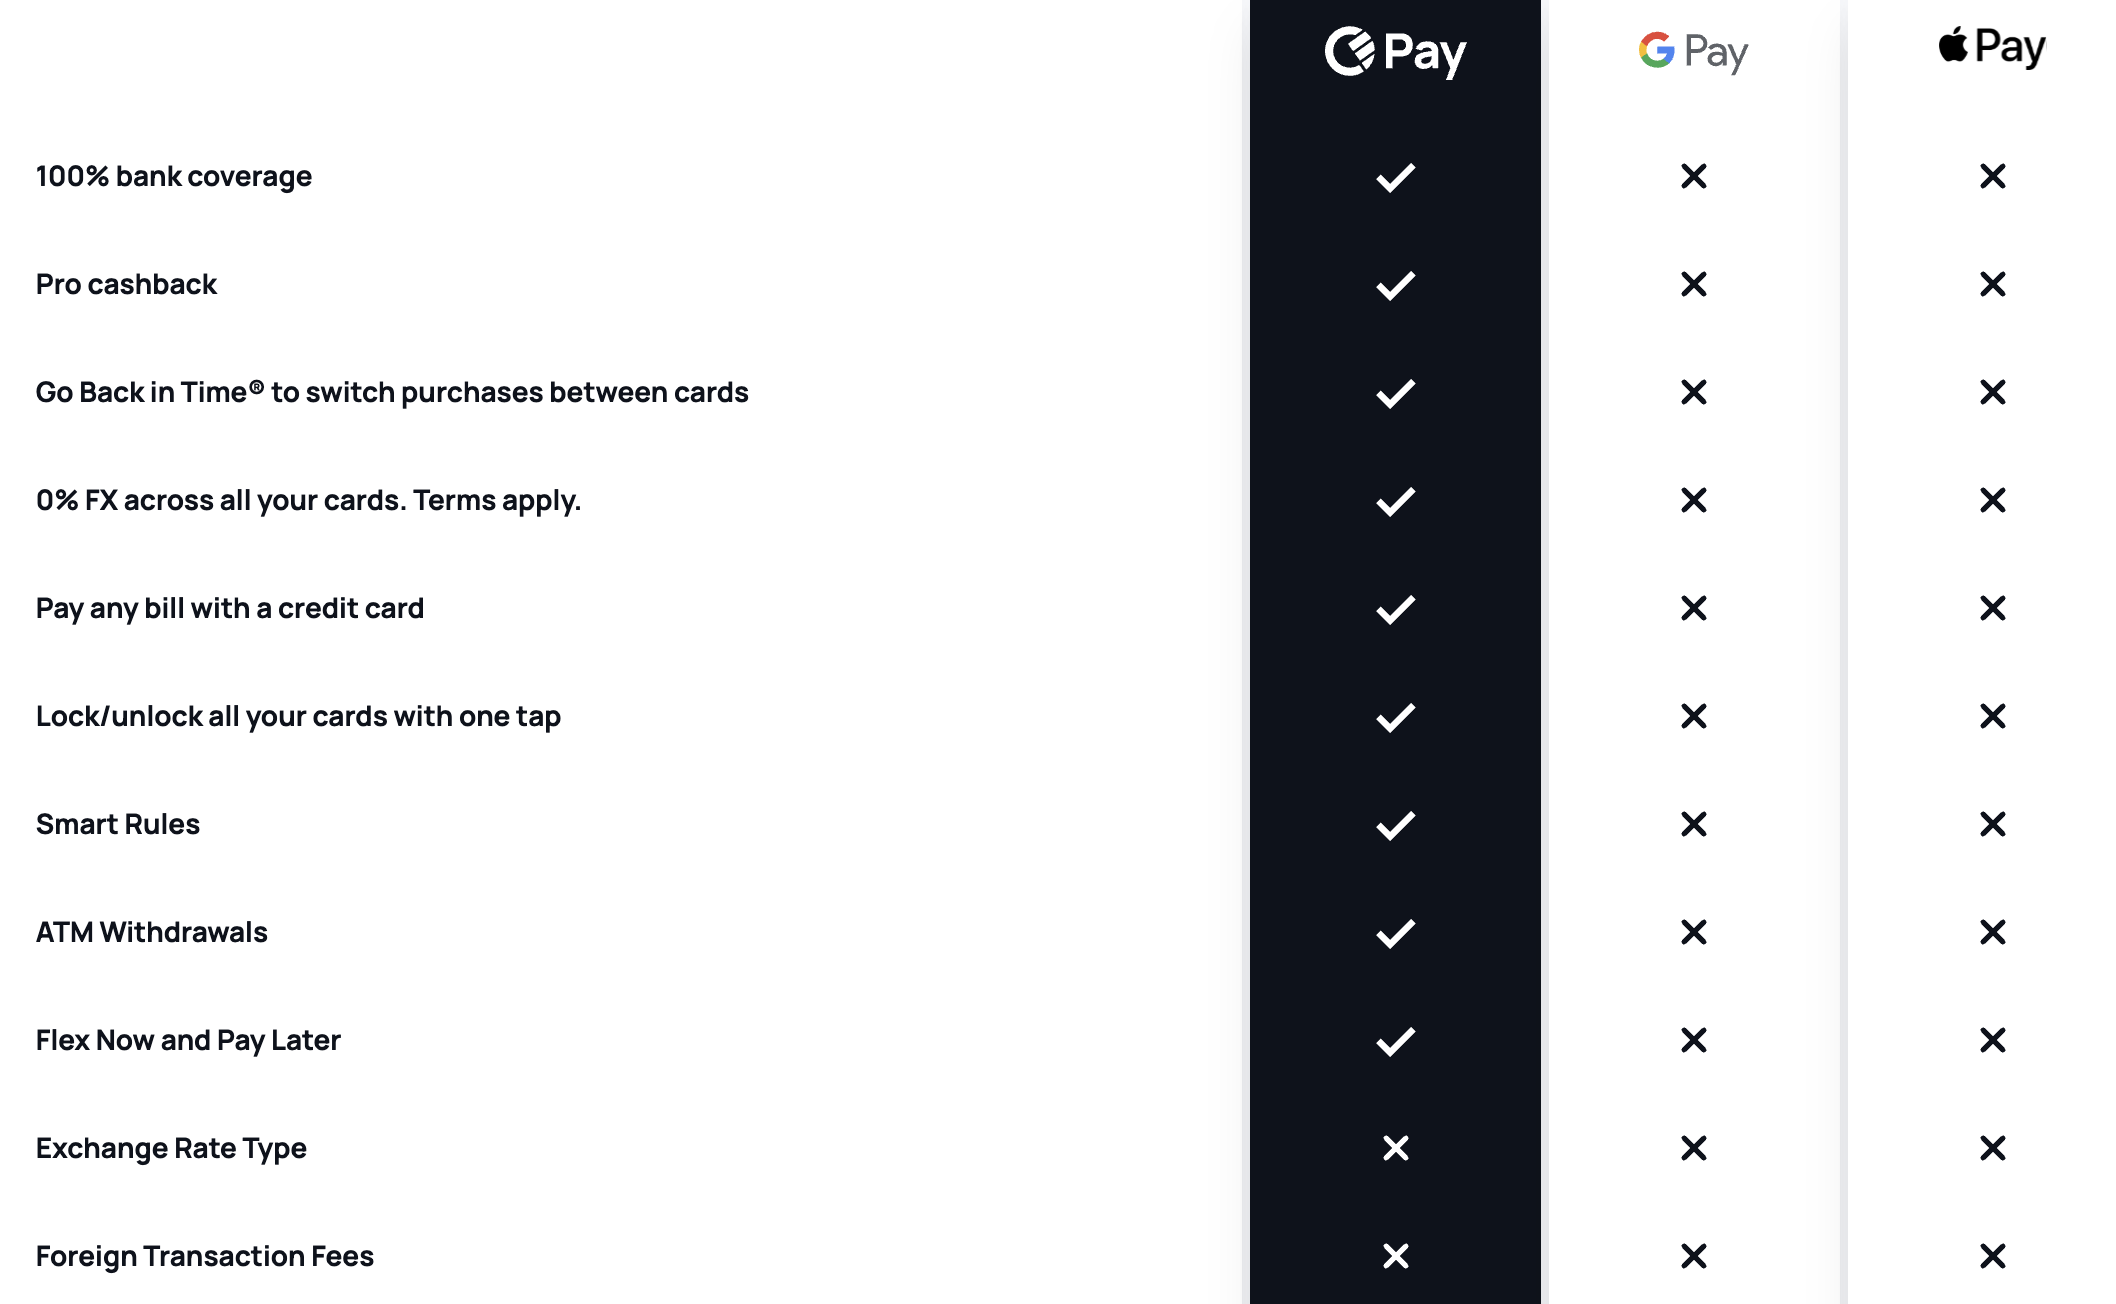
The pros and cons at a glance
Before going deeper, here is how Curve's strengths and weaknesses stack up for an EU user.
- Card aggregation. Consolidate multiple payment cards into one physical Mastercard and manage them from a single app.
- Go Back in Time. Switch a past transaction to a different underlying card for up to 120 days when it works as intended.
- Smart rules. Automate which card a purchase routes to, useful for separating personal and business spending.
- One app for spending. Spending analytics and transaction categorisation across all your linked cards in one place.
- Free plan still has tight limits. Linked cards are now unlimited, but the free plan still allows only 3 Go Back in Time switches a month and €250 of foreign spending before a 2.99% fee.
- Customer service crisis. Reported 3 to 4 week minimum response times with no phone support and cards blocked during travel with no emergency path.
- Cashback often does not work. Many issuers exclude purchases routed through Curve from rewards, defeating a key reason to use premium cards.
- Lost Section 75 protection. Because the issuer sees the merchant as Curve, Section 75 credit-card protection no longer applies to expensive purchases.
What We Don't Like About Curve Card
Our testing revealed significant issues that make Curve difficult to recommend:
Free plan limits that remain: Curve's EEA subscription schedule, published on 17 November 2025, no longer caps how many cards you can add, on free Curve Pay or on the paid plans. Curve's note of the terms changes says the funding-source limit was removed for every tier. The free plan still allows only 3 Go Back in Time switches in a rolling 30-day period, on payments up to 30 days old, and €250 of foreign spending before a 2.99% fee.
Customer Service Crisis: Support response times of 3-4 weeks minimum with no phone support option. Users report cards blocked during travel with no emergency resolution path.
Cashback Problems: Many credit card providers don't offer cashback or rewards when purchases route through Curve, defeating a key reason to use premium cards in the first place.
CostsCurve Card Pricing and Plans
Curve offers four tiers, though we found limited value in most.
The paid plans only make sense if you regularly exceed €250 monthly in foreign spending, but competitors offer better rates without monthly fees.
| Feature | Pay (Free) | Pay X (€5.99/month) | Pay Pro (€9.99/month) | Pay Pro+ (€17.99/month) |
|---|---|---|---|---|
| Monthly Cost | €0 | €71.88/year | €119.88/year | €215.88/year |
| Card Delivery | €5.99 | €3.99 | €0 | €0 |
| Cards Supported | Unlimited | Unlimited | Unlimited | Unlimited |
| Go Back in Time | 3 per month | 3 per 60 days | Unlimited (90 days) | Unlimited (120 days) |
| FX Allowance | €250/month | €3,333/month | €50,000/month | €100,000/month |
| Excess FX Fee | 2.99% | 1% | 1% | 1% |
| ATM Allowance | €0 (2% fee) | €300/month | €500/month | €1,000/month |
| Cashback | 1% outside Europe | 1% outside Europe | +1% at 6 retailers | +1% at 12 retailers |
| Our Assessment | Nearly useless | Poor value | Overpriced | Competes with Revolut Metal |
Safety and Regulation
Curve operates under proper EU regulation through Curve Europe UAB in Lithuania (Bank of Lithuania oversight) and Curve UK Limited in the UK (FCA regulation). Your funds receive standard e-money institution (learn about managing your finances in our 11-point financial checklist) protection.
However, using Curve removes Section 75 credit card protection since your card issuer sees transactions as coming from Curve, not the original merchant. This creates additional risk for expensive purchases.
AppTrading Experience and App Issues
The Curve app provides decent spending analytics and transaction categorization when it works. However, we encountered:
- Frequent app crashes and login failures
- False positive fraud detection blocking legitimate purchases
- Payment processing errors even with sufficient underlying balances
The onboarding process is straightforward with standard KYC requirements, but card delivery can take 1-2 weeks.
FXForeign Exchange Performance
This is where Curve shows both its biggest weakness and potential strength:
Free Tier Problems:
- Severe €250 monthly limit before 2.99% excess fees kick in
- Base rates include Mastercard markup (approximately 0.72% above interbank)
- Essentially unusable for regular travelers due to low limits
Paid Plan Benefits:
- Pay X: €3,333 monthly FX-free allowance
- Pay Pro: €50,000 monthly FX-free allowance
- Pay Pro+: €100,000 monthly FX-free allowance (essentially unlimited for most users)
- Weekend FX markup on the free plan (1.5% on Saturdays and Sundays; paid plans have none)
- True fee-free spending within limits on paid plans
The Value Question: While paid plans offer genuine FX benefits, you're paying €71.88-€215.88 annually. Competitors like Wise offer mid-market rates with transparent low fees, while Revolut provides competitive rates with much more comprehensive banking features for similar costs.
SupportCustomer Support Quality
Customer support represents Curve's most serious failing. We experienced:
- 3-4 week minimum response times for standard queries
- No phone support availability
- Unresponsive email and in-app chat
- Trustpilot rating of just 2.4/5 stars
Users report cards being blocked during travel with no emergency contact options, making any issue potentially catastrophic.
RewardsCashback and Rewards Limitations
A critical issue we discovered: many credit card providers don't offer cashback or rewards when purchases route through Curve. Since card issuers see transactions as merchant category "6051 - Quasi-cash," they often exclude these from rewards programs.
This defeats the primary purpose of using premium rewards cards. If you're not earning cashback on your American Express or Premium Visa, why use them through Curve at all?
AlternativesHow Curve Compares to Alternatives
Versus Revolut: Revolut offers better FX rates, comprehensive banking services, superior customer support and better value for money.
Versus Wise: Wise dominates for international spending with true mid-market rates and transparent fees. No monthly limits or weekend penalties.
Curve's distinctive feature is card aggregation with retroactive switching. The free plan now allows unlimited cards, but the three-switch cap and the support record still get in the way for free users. Also we recommend having an emergency fund, which should be outside of any of your Curve Cards.
Best fitWho Should Consider Curve Card
Curve might work for:
- Business professionals needing expense separation between personal and business cards
- Light international spenders under €250 monthly who can tolerate poor support
Things to Be Aware Of
- Free plan switching and FX caps remain, even though linked cards are now unlimited
- Customer support challenges makes any issue a major problem
- Cashback and rewards often don't work with underlying cards
- Complex fee structure with multiple charges that stack unexpectedly
- No emergency support if card blocked during travel
Final Verdict
Curve Card represents a good idea poorly executed. While card aggregation and Go Back in Time features address real needs, the operational reality falls far short of the marketing promises.
The severe free tier limitations, uncompetitive FX rates, customer service failures, and cashback issues make it difficult to recommend for most EU users. We found alternatives like Revolut, Wise, or modern traditional banks provide better overall value. Also check out the highest yielding savings accounts in Europe.
Curve might improve with their recent €37M funding, but current execution problems make it a risky choice for your primary payment method.
FAQFrequently Asked Questions
Curve operates under proper EU regulation through Lithuanian and UK authorities. However, poor customer support makes resolving issues extremely difficult if problems arise.
No, Curve is a debit card service that doesn't impact your credit score. However, it may interfere with earning rewards on underlying credit cards due to how transactions are categorized.
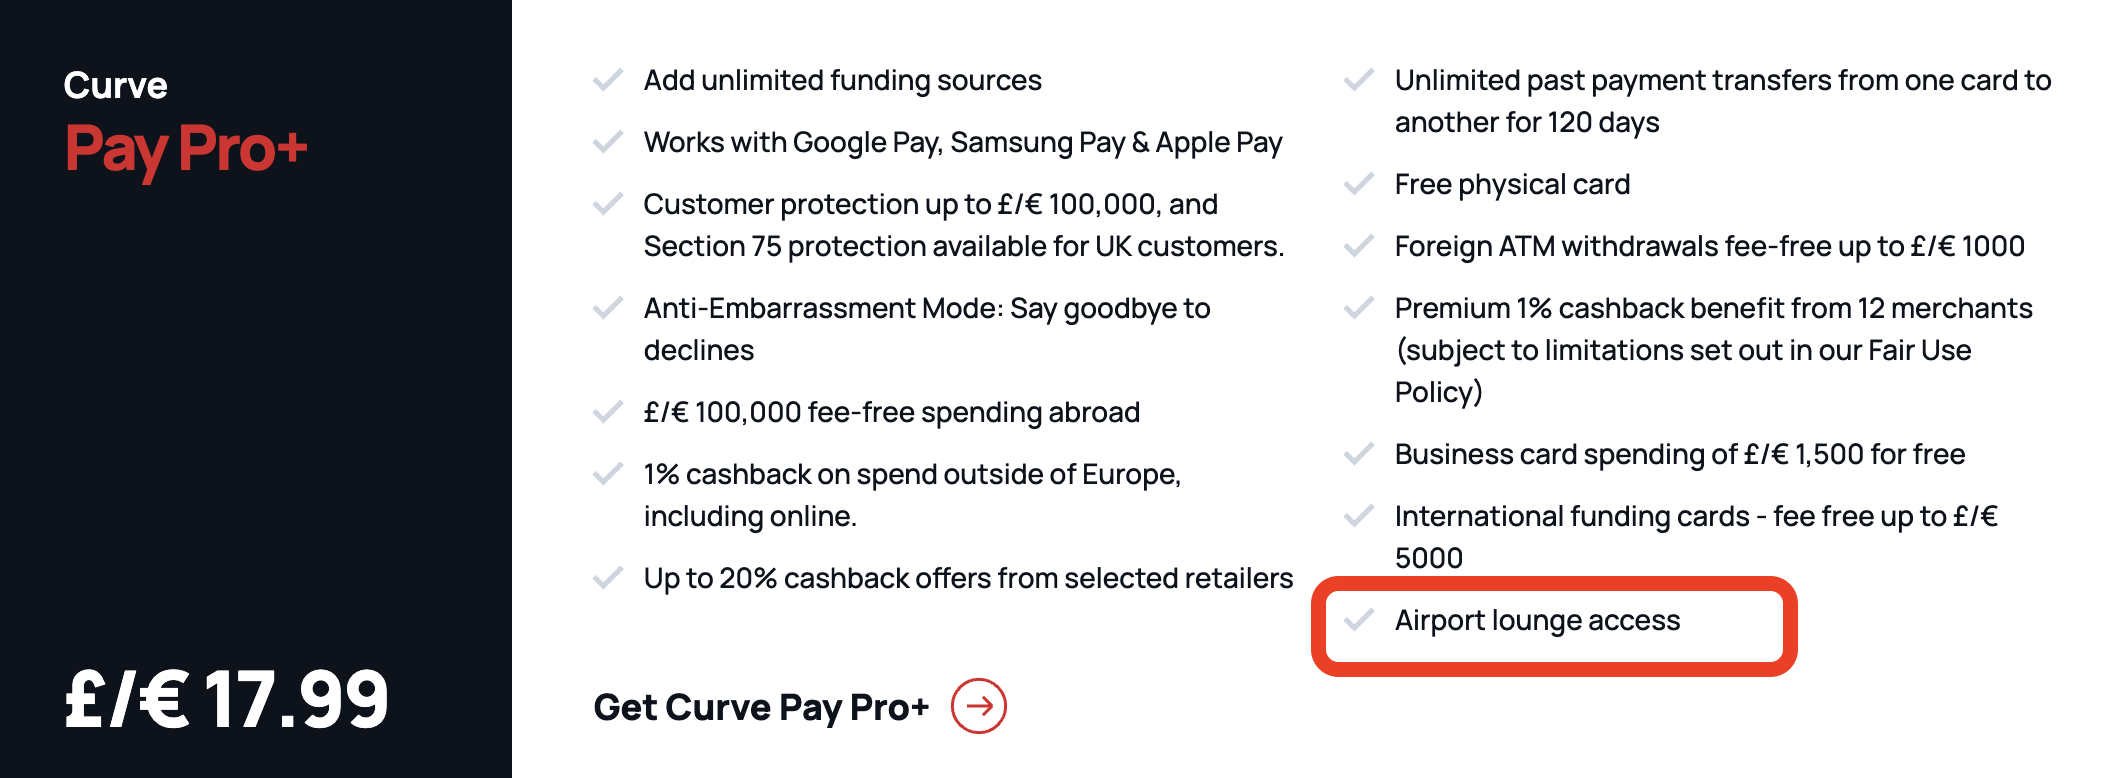
Curve advertises "airport lounge access" for Pro+ users but actually provides discounted access at €30 per person through LoungeKey, not free lounge entry as the marketing implies.
Yes, but the free tier has no ATM allowance (2% fee or €2 minimum on all withdrawals). Paid plans offer meaningful allowances: €300 (X), €500 (Pro), €1,000 (Pro+) monthly.
Many card issuers classify Curve transactions as "quasi-cash" and exclude them from rewards programs, defeating the purpose of using premium cards.
Curve runs referral promotions from time to time, with conditions set per campaign. Check the Curve website or app for any current offer. Given the free tier's severe limitations, consider whether the service meets your long-term needs before signing up.
This is a major risk. With no phone support and weeks-long response times, a blocked card during travel can become a serious problem with no rapid resolution.
Curve earns interchange fees from merchants plus foreign exchange markups, monthly subscription fees for paid plans, and various transaction charges.
Yes, you can cancel anytime through the app. However, getting customer support to resolve any final issues may take weeks.
On the airport-lounge point above, here is what Curve actually advertises for Pay Pro+ members.
Featured partner: Capital at risk. Provider of the investment services is Lightyear Europe AS for the EU. Terms apply: lightyear.com/terms. Seek qualified advice if necessary. This is not investment advice. Sponsored Link.