 Featured partnerSign up to Lightyear and get up to €100 in a free fractional shareCapital at risk, terms apply. Seek guidance if necessary. Claim Up to €100 Capital at risk, terms apply. Seek guidance if necessary.
Monefit SmartSaver
€5 welcome cash bonus plus 0.25% on qualifying net investments during your first 90 days. For eligible new customers. Terms apply.
The 4.9/5 reflects how the platform performs on the things I can verify: a clean interface, returns credited daily, a published price list, a small withdrawal that arrived as described, and audited 2025 accounts from Creditstar. It does not offset the missing deposit guarantee, the concentration in a single lender group, or the limits on withdrawing larger sums.
- Main Account: expected 7.50% APY with returns credited daily and no fixed term. The expected return is not guaranteed.
- Vaults: expected APYs from 9.42% for 12 months to 10.52% for 24 months, with accumulated returns forfeited on early closure.
- Access: up to €1,000 per calendar month through the instant route. Larger withdrawals normally take up to 10 Estonian business days plus bank time.
- Protection: no EU deposit guarantee and no investor compensation scheme. Capital is at risk and the position depends on Creditstar Group.
Monefit SmartSaver pays an expected 7.50% APY on a flexible Main Account and up to 10.52% APY on money locked into a 24-month Vault. Neither number carries an EU deposit guarantee, and no investor compensation scheme sits behind the product. Your money funds claims arising from consumer loans issued by Creditstar Group companies. So the decision is narrow: does the extra expected return compensate you for Creditstar credit risk and for withdrawal terms that can slow down under stress?
Not Monefit. Use a protected account with dependable access.
Compare the Main Account with Go & Grow before committing.
Consider Vaults only after accepting the early-exit consequences.
Treat Monefit as a capped position, not as a replacement for cash.
My Monefit portfolio and what I have tested
I use Monefit as a satellite position, not as my emergency fund.
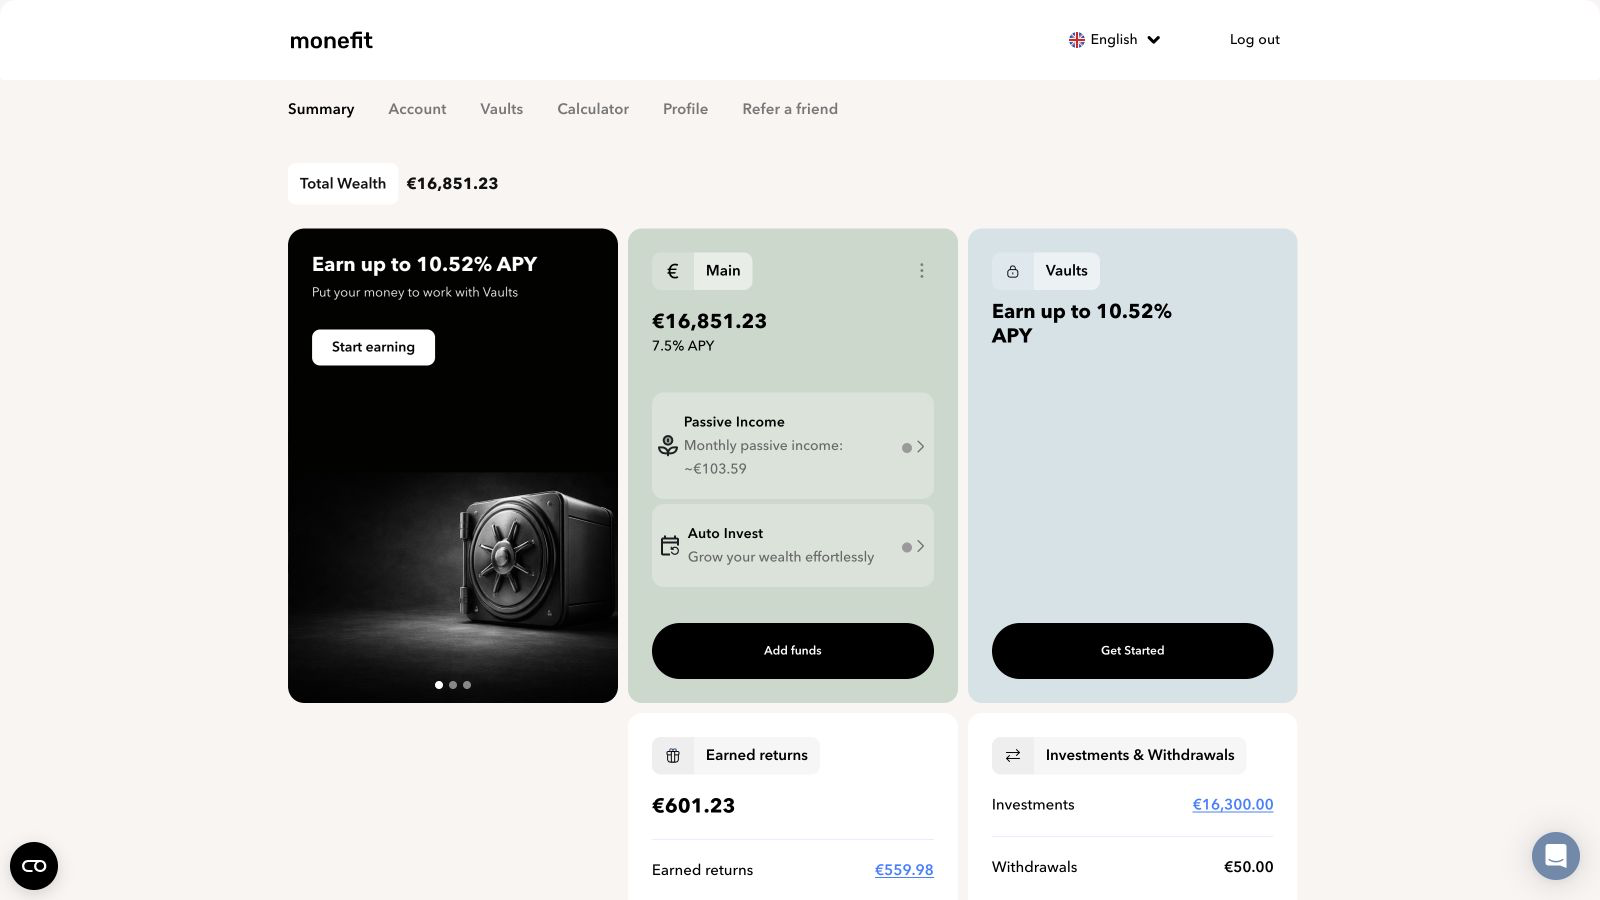
My own summary screen on 9 August 2026 showed total wealth of €16,851.23, with an expected Main Account rate of 7.5% APY. Behind that figure sit €16,300 of investments, €601.23 of earned returns and €50 of withdrawals. The figures reconcile: €16,300 plus €601.23 minus €50 gives €16,851.23.
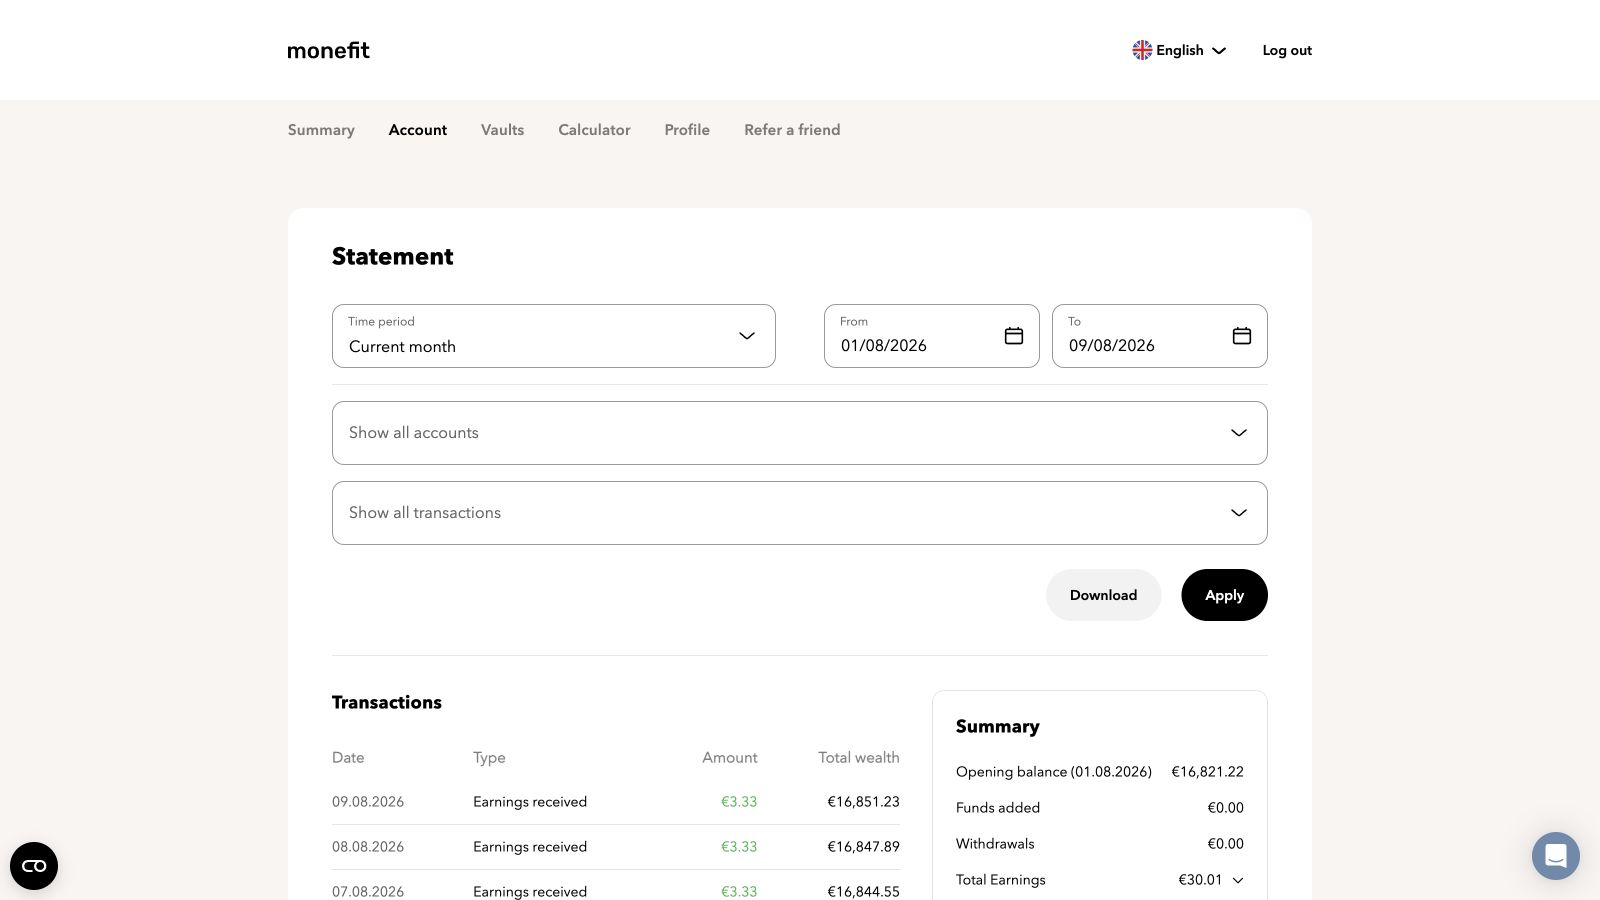
The account statement fills in the detail. It recorded €3.33 credited on each day from 1 to 9 August 2026, taking current-month earnings to €30.01. That daily rhythm is what the 7.5% headline looks like in practice at my balance, and the rate is expected rather than fixed, so those daily amounts can move.
- High expected return. The flexible Main Account currently shows 7.50% APY, with daily crediting.
- Simple interface. The dashboard keeps the balance, earned returns and estimated monthly income easy to follow.
- Free bank transfers. Funding and withdrawing by bank transfer is free.
- Optional fixed terms. Vaults offer a higher expected APY when you can genuinely lock the capital.
- No protection scheme. No EU deposit guarantee or investor compensation scheme covers the balance.
- Creditstar concentration. The underlying claims come from one lending group, despite diversification across many borrowers.
- Withdrawal limits. Only €1,000 per calendar month qualifies for the instant route.
- Limited transparency. You do not select individual claims or receive loan-level detail.
How Monefit SmartSaver works
Monefit Investments OÜ operates SmartSaver. It is an Estonian company inside Creditstar Group. When you fund an account, your money buys exposure to claims arising from consumer loans issued by Creditstar Group companies. You are not opening a savings account and you are not lending to a bank. You are taking a position in consumer credit.
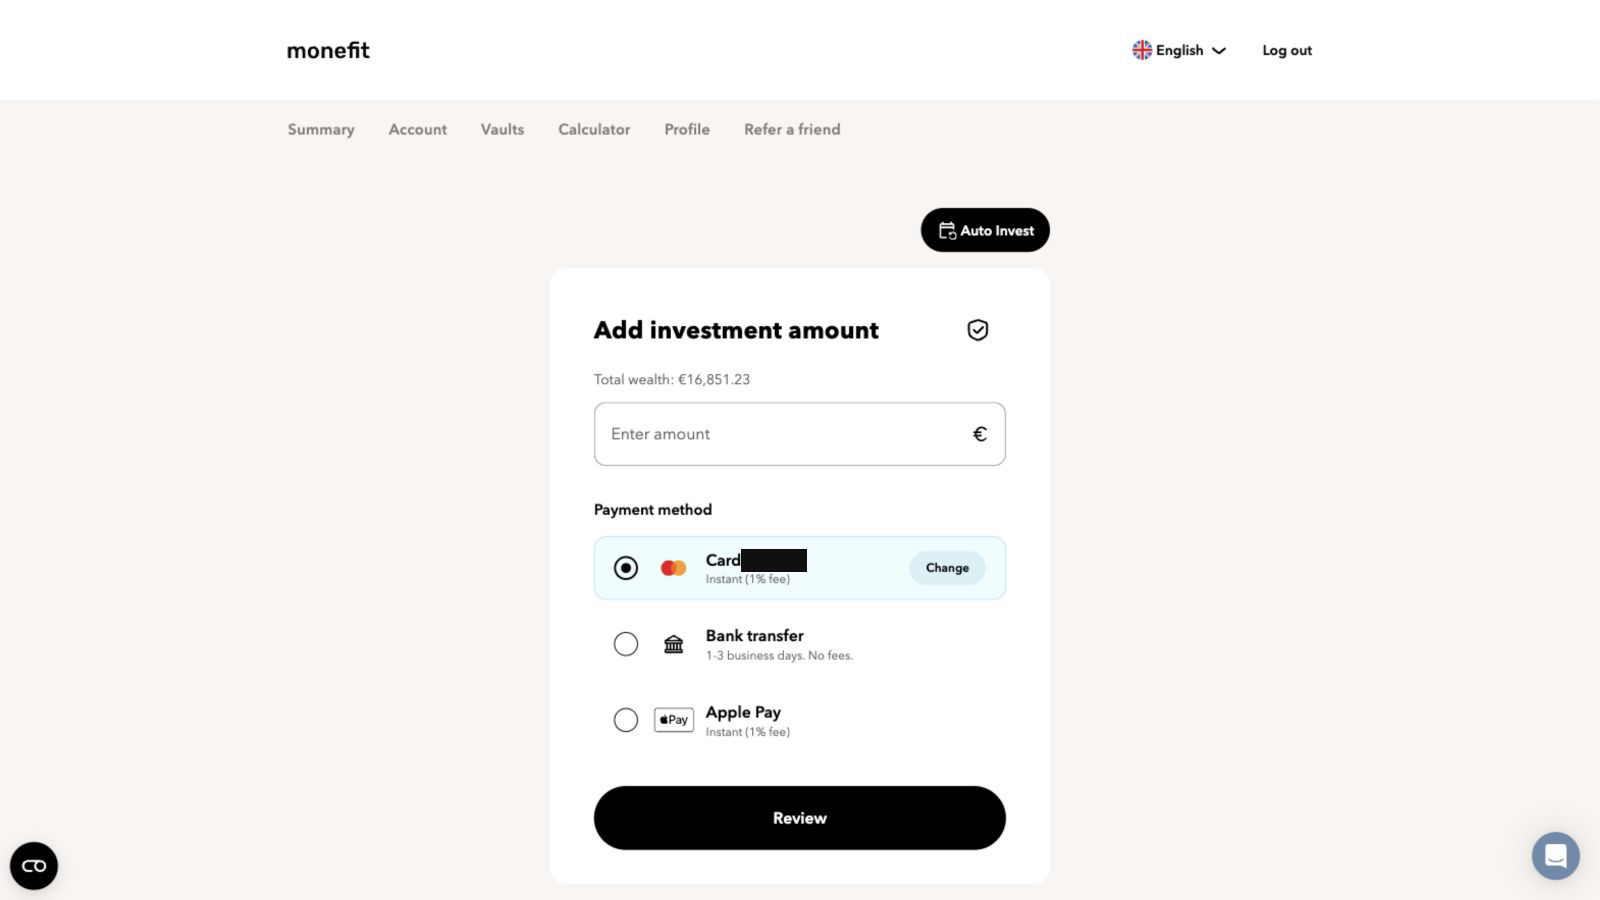
The mechanics are deliberately simple. The Main Account takes €10 or more, runs with no fixed term, and credits returns daily. Vaults take €100 or more and lock the money for a set period. Across both, the combined maximum is €500,000.
Monefit SmartSaver now has an official Android app. The iOS app is still listed as coming soon.
That simplicity costs you transparency. You do not choose individual claims and you do not receive loan-level detail, so you cannot inspect the credit quality behind your position the way you could on a marketplace that publishes its loan book. You also cannot sell an individual claim to a third party. Any sale request goes back through Monefit.
These are current company-reported product-page figures, not audited or independently verified proof of safety. The audited 2025 report says the SmartSaver investor base grew 64% during the year and the average investment account was €15,900.
Expected returnsMain Account versus Vaults
The Main Account carries an expected 7.50% APY, with no fixed term and returns credited daily. The word that matters is expected. The rate is set by Monefit, it is not contractually guaranteed, and it can move.
Three rules decide whether that premium of 1.92 to 3.02 percentage points is worth taking.
- A new Vault has a 10-day funding window, so the capital needs to be ready when you open it.
- Closing a Vault early forfeits the returns accumulated inside it.
- An early exit is not immediate, so plan for up to 30 business days.
The rate maths is the easy part. The harder question is whether you want to hold two years of exposure to a single lending group for roughly three extra percentage points a year, with no ability to step out cleanly if your view changes.
AccessWithdrawals and fees
Funding and withdrawing by bank transfer is free. Card, Apple Pay and Google Pay transactions carry a 1% fee after the first seven days, in either direction. Recurring Auto Invest card payments stay free.
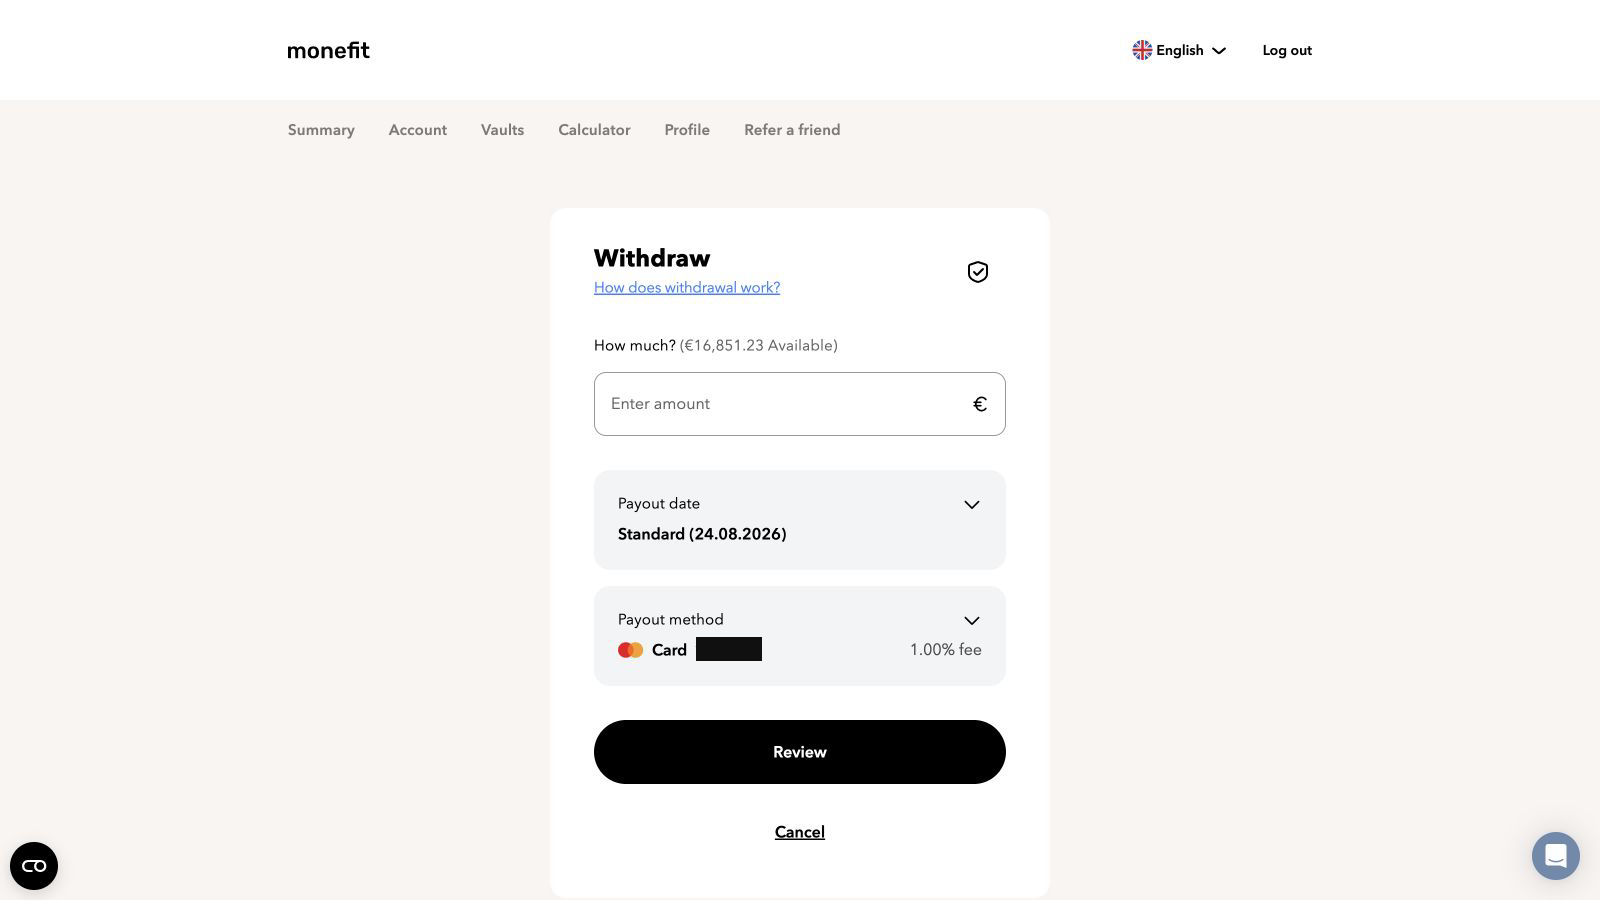
The normal minimum withdrawal is €50, unless you are closing an account with a smaller balance. Under stressed liquidity, Monefit can suspend payouts and pay them pro rata in instalments.
Is Monefit SmartSaver safe?
Start with what is not there:
- No EU deposit guarantee covers your balance.
- No investor compensation scheme covers the product.
- Expected returns are not guaranteed, and neither is repayment of your capital.
- Partial or total loss is possible.
Add what you cannot see or control. You do not select individual claims, you do not receive loan-level detail, and you cannot sell a claim to a third party on your own initiative. Sale requests route back through Monefit.
Then add the structural point. Your money spreads across many consumer loans, which dilutes the risk of any single borrower defaulting. It does not spread across many lenders. Every one of those loans originates inside the Creditstar lending ecosystem, so the position concentrates on one group's underwriting, funding and operations.
None of this predicts failure. It explains pricing. Protected euro cash pays what it pays because a guarantee scheme stands behind it, and you can compare those rates in my roundup of high-yield euro savings accounts in Europe. Monefit pays 7.50% because you carry the credit and liquidity risk that a guarantee would otherwise absorb. The gap is compensation for a real risk.
Investor reportsWhat other investors report
Monefit holds 4.7 out of 5 from 1,565 Trustpilot reviews as of 10 August 2026. Monefit invites reviews and runs a paid Trustpilot profile, so treat the score as sentiment evidence rather than safety evidence.
- Simple setup and clear dashboard
- Visible daily returns
- Helpful support
- Instant withdrawals within the allowance
- €1,000 instant monthly limit
- 1% card fee
- Creditstar concentration
- Limited loan-level transparency
- Vault early-exit rules
I leave Reddit threads and affiliate blog claims out of the risk assessment unless I can check them against the platform's own terms or the audited accounts.
Financial healthWhat Creditstar's 2025 audited numbers show
Your return depends on Creditstar Group, so its accounts are the most useful risk document available. KPMG Baltics OÜ issued an unmodified opinion on the 2025 financial statements, prepared under IFRS as adopted by the EU. An unmodified opinion means the auditor found the statements fairly presented. It does not guarantee that investors get their money back.
The maturity gap is the number I keep returning to. Management states that short-term funding is repeatedly extended and that most bond maturities falling due in early 2026 were refinanced. That is a normal way for a consumer lender to operate, and it has worked so far. It also means the business depends on continued access to refinancing, which is a condition set by credit markets rather than by the company.
Read Creditstar Group's full 2025 annual report.
Closest alternativeMonefit versus Go & Grow
Go & Grow is the closest comparison for most EU investors weighing Monefit, because it targets the same job: a flexible, higher-yielding home for money that is not core cash. The two differ most on access and on what sits underneath.
Expected and target returns are not guaranteed. Capital is at risk with both products.
Monefit wins when you accept Creditstar risk, want the extra expected return, and will not need more than €1,000 quickly. Go & Grow wins when flexible access to a larger balance matters more to you than 1.5 percentage points, and my full assessment sits in the Go & Grow review for EU investors. Neither belongs in the protected core of an emergency fund, because neither carries a state guarantee.
Best fitWho Monefit is for, and who should avoid it
An investor who already holds protected cash, understands consumer-credit risk, wants a higher expected return on a defined slice of capital, and can leave that slice alone.
A first emergency fund, money needed at short notice, investors demanding loan-level transparency, or any position whose total loss would cause serious harm.
I would not let any single non-guaranteed consumer-credit provider hold a share of my net worth that would damage me if it went to zero.
Welcome offerMonefit welcome bonus
Eligible new customers signing up through our link receive a €5 welcome cash bonus plus 0.25% on qualifying net investments during their first 90 days. The 0.25% component gives €2.50 on €1,000, €12.50 on €5,000 and €25 on €10,000, before adding the separate €5 welcome cash bonus. These examples assume no withdrawals during the qualifying period. Terms apply.
Withdrawing during the window reduces the qualifying net investment, so the bonus is recalculated on the lower figure. Terms apply and are set by Monefit.
Final verdict
Monefit belongs in a portfolio as a capped satellite allocation. Emergency money needs to sit somewhere protected and instantly accessible, and this is neither of those things. Monefit is an investment platform, and the capital is exposed to one lender group. I hold it as a slice I could afford to lose, sized against my wider holdings and not against my monthly outgoings.
The 4.9/5 reflects execution. My own account on 9 August 2026 showed €16,851.23 in total wealth, daily returns credited without interruption, a published price list, and a small withdrawal that completed as described. Creditstar's audited 2025 accounts also give more disclosure than most platforms in this bracket provide.
The financial position still carries real risk. No deposit guarantee or investor compensation scheme covers the money. Access above €1,000 per calendar month depends on business-day processing, normally within 10 business days, and payouts can be suspended or made pro rata under stress. Net debt to equity stood at 4.86x against a 5.0x covenant ceiling, and current liabilities exceeded current assets. The score measures the product and the level of disclosure. It says nothing about whether my capital will be returned.
FAQFrequently asked questions
No on both counts. SmartSaver is an investment product that funds claims arising from consumer loans issued by Creditstar Group companies. No EU deposit guarantee and no investor compensation scheme applies. Expected returns are not guaranteed, and partial or total loss of capital is possible.
The instant route covers up to €1,000 per calendar month. Anything above that goes through the standard process, which takes up to 10 Estonian business days plus your own bank's processing time. Under stressed liquidity, Monefit can suspend payouts and settle them pro rata in instalments. The normal minimum withdrawal is €50, unless you are closing an account with a smaller balance.
Use bank transfers, which are free in both directions. The 1% fee applies to card, Apple Pay and Google Pay funding or withdrawals after the first seven days. Recurring Auto Invest card payments remain free.
You forfeit the returns accumulated inside that Vault, and the exit is not immediate, so plan for up to 30 business days. Two related rules are worth knowing before you open one: the minimum is €100, and a new Vault has a 10-day funding window.
Both are true at different levels. Your money spreads across many consumer loans, which dilutes single-borrower risk. All of those loans originate inside the Creditstar lending ecosystem, so the position stays concentrated on one group. You do not select individual claims or receive loan-level detail, and you cannot sell a claim to a third party. Sale requests go back through Monefit.
Automated checks usually fail for ordinary reasons: a low-quality document scan, glare across the photo page, an expired document, or a name or address that does not match the details you registered with. Retry with a clear scan of a valid document and details that match your registration. If the automated check still rejects you, contact Monefit support and ask for a manual review.
Tax treatment depends on your country of residence, and the classification, reporting duties and rates vary across the EU. Check your national rules or take advice from a qualified tax adviser in your country of residence before you invest.
Featured partner: Capital at risk. Provider of the investment services is Lightyear Europe AS for the EU. Terms apply: lightyear.com/terms. Seek qualified advice if necessary. This is not investment advice. Sponsored Link.